Earn 7.12% Tax-Free: The Ultimate Guide to Pag-IBIG MP2 Savings
If you've been looking for a safe place to grow your hard-earned money, the universe (and the Philippine government) has just given you a massive green light. Pag-IBIG Fund recently declared a record-breaking ₱64.34 billion in dividends for 2025, marking the highest payout in its 45-year history.
Even better? The dividend rate for the Modified Pag-IBIG 2 (MP2) Savings program has climbed to a staggering 7.12%. In a world where traditional bank savings accounts offer less than 1% interest, the MP2 program is a financial game-changer.
Whether you are a local employee, an Overseas Filipino Worker (OFW), or even a foreign expat residing in the Philippines, here is everything you need to know to maximize your wealth with MP2.
What Makes MP2 So Special?
The Modified Pag-IBIG 2 (MP2) is a voluntary, 5-year savings facility designed for active Pag-IBIG members. It is specifically built to yield higher dividends than the regular mandatory savings. Here is why financial advisors constantly recommend it:
- It is 100% Tax-Free: This is the biggest perk. If you put your money in a commercial bank's time deposit, the government automatically deducts a 20% withholding tax from your earnings. With MP2, your dividends are completely tax-free—you keep every single centavo.
- Government-Guaranteed: Unlike stocks or crypto, your principal investment is protected by the Philippine government. You will never lose the exact amount you put in.
- Highly Accessible: You can start investing for as low as ₱500 per remittance. There is no maximum limit, though one-time deposits exceeding ₱500,000 require a personal or manager's check.
Who Can Open an Account?
MP2 is incredibly inclusive. You can open an account if you fall into any of these categories:
- Active Pag-IBIG Members: Any Filipino currently contributing to the regular Pag-IBIG I fund.
- Pensioners and Retirees: Former members with at least 24 months of previous contributions can still invest.
- Overseas Filipino Workers (OFWs): It is a brilliant way for OFWs to prepare for their eventual return home.
- Foreign Expats: Yes, foreigners legally working in the Philippines who are compulsorily covered by the SSS can (and should) participate in Pag-IBIG, giving them full access to the high-yield MP2 program.
Pro-Tips to Maximize Your Earnings
Choose "Compounding" Over "Annual Payout"
When you apply, you will be asked how you want to receive your dividends: annually or compounded. Unless you are a retiree who desperately needs the yearly cash flow to pay for groceries or maintenance meds, always choose compounded savings.
With compounding, your earned dividends are automatically added to your principal amount. The following year, your new, larger total balance will earn interest. This creates a snowball effect that maximizes your returns by the end of the 5-year term.
Front-Load Your Savings
Because Pag-IBIG calculates dividends based on your Average Monthly Balance (AMB), depositing a larger lump sum early in the year will earn you significantly more interest than depositing smaller amounts at the end of the year. If you have a 13th-month pay or a bonus, park it in MP2 immediately!
Take Advantage of Digital Payment Channels
You don't need to endure long lines at a government branch to fund your account.
- For locals: You can pay easily via GCash, Maya, or your online banking apps (like BDO or UnionBank) through the bills payment section.
- For OFWs: Funding your account from abroad is easier than ever. You can use international remittance partners like Smiles Mobile Remittance (popular in Japan), Profee (in Europe), or via overseas branches of AUB and PNB.
The Golden Rule: Don't Touch It for 5 Years
MP2 is a long-term commitment. The program requires a 5-year lock-in period.
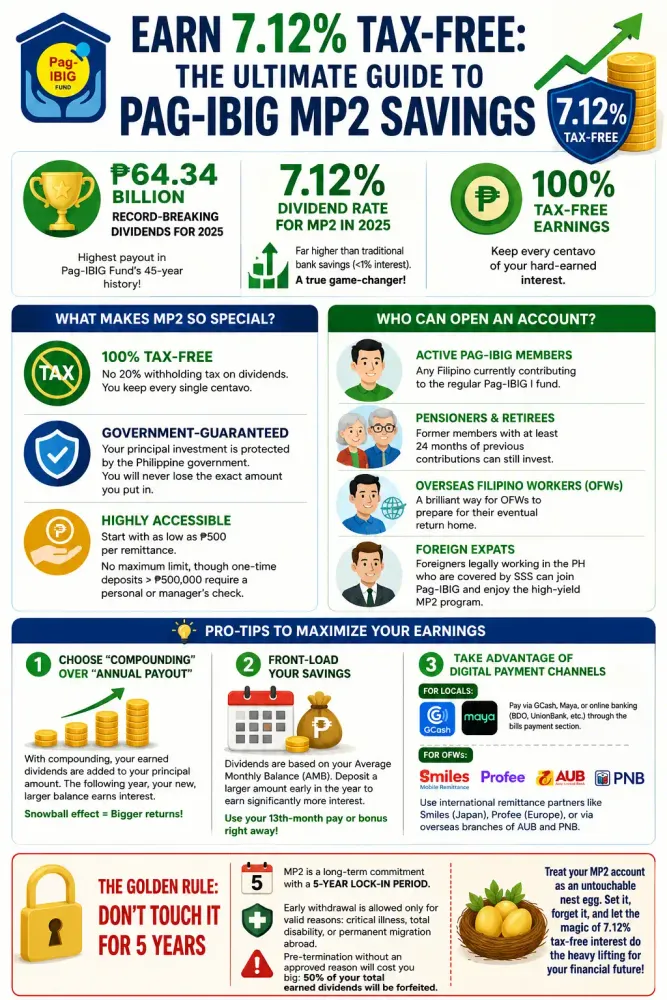 While the system allows for early withdrawal in cases of severe emergencies (like critical illness, total disability, or permanent migration abroad), withdrawing early simply because you want to buy a new gadget comes with a heavy penalty. If you pre-terminate your account without a valid reason approved by the fund, you will forfeit 50% of your total earned dividends.
Even the most advantageous savings plans won’t work without basic financial discipline. If you’re just starting to build an emergency fund or looking for ways to set aside more money each month, you should first check out this practical guide to saving and surviving inflation in the Philippines in 2026.